A lower DAP supplier price can leave you with separate import payments. Start with the seller's invoice, add the amounts your business will pay outside it, and compare delivery to the same point. The worked example below shows how an €11,000 offer can require more cash than a €12,800 offer.
This guide is for business buyers comparing goods-sale offers. Keep any separately booked transport quote alongside the purchase offer.
Worked example: a lower invoice needs more cash
Invented budgeting example. A Portuguese business imports the same equipment from outside the EU to the same Porto warehouse bay. Assume the parties have confirmed workable import arrangements and all the amounts below. These are invented quoted amounts, including any taxes payable on the quoted services, rather than calculated tax or duty rates. In this example, the DAP buyer pays import VAT in cash at import.
| Payment | DDP and DAP offers |
|---|---|
| Seller's full invoice | DDP: €12,800 DAP: €11,000 |
| Import clearance fee | DDP: Included in invoice DAP: €100 separately |
| Import duty | DDP: Included in invoice DAP: €300 separately |
| Import VAT | DDP: Included in invoice DAP: €2,300 separately |
| Agreed unloading service | DDP: €100 separately DAP: €100 separately |
| Planned cash payments | DDP: €12,900 DAP: €13,800 |
The DDP calculation is €12,800 + €100 = €12,900. The DAP calculation is €11,000 + €100 + €300 + €2,300 + €100 = €13,800. The lower invoice therefore requires €900 more cash for these invented offers.
The two totals cover the stated purchase and delivery payments before any later VAT deduction. Record when each payment falls due, and compare any confirmed VAT treatment separately with your tax contact. If the DAP clearance fee or an unloading price is still missing, keep that offer incomplete rather than using the example's figures.
Who handles import clearance under DDP and DAP?
- DDP: the seller handles import clearance and applicable import duties and taxes under the normal Incoterms 2020 allocation.
- DAP: those import responsibilities fall to the buyer.
Under both rules, delivery is normally on the arriving vehicle, ready for unloading. Confirm who provides the equipment and labour. If unloading costs are already the seller's responsibility under its carriage contract, they cannot be charged to the buyer separately unless otherwise agreed. ICC: DAP and DDP provisions.
For a DDP offer, ask the seller to identify its clearance contact and the documents you must provide. A workable arrangement matters as much as the label on the offer.
Make the offers cover the same purchase
Give each supplier the same goods specification, quantity and receiving requirements. Write the exact delivery point, such as the agreed receiving bay at your Porto warehouse, and the rule and edition: DDP or DAP, Incoterms 2020.
Keep the currency, payment dates, quotation validity and conditions for a price change with each offer. Incoterms allocate specified sale responsibilities; the sale contract also needs its payment and other agreed terms. ICC: incorporating the rules into a sale contract.
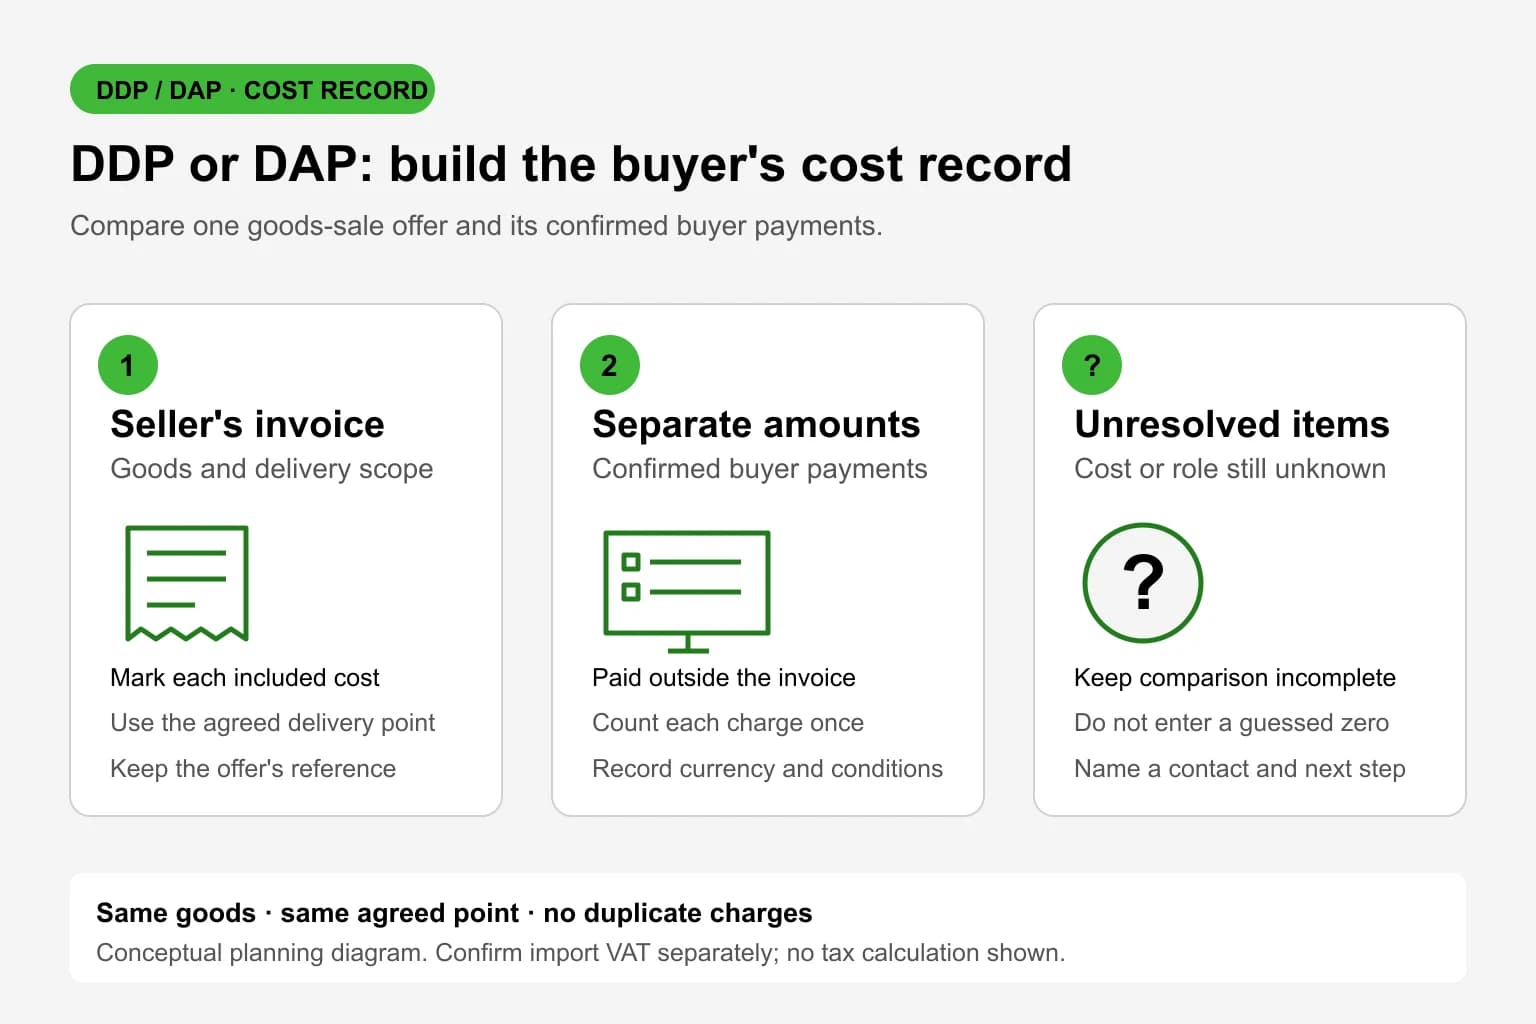
Put each buyer payment in one record
- Seller's invoice: record the full amount payable, its tax treatment and exactly what it covers.
- Separate payments: add clearance fees, duties, import VAT, unloading and other relevant amounts that your business must pay outside that invoice. Record the payee and due date.
- Unresolved items: name the person who will confirm the amount or condition. Leave an unknown as “awaiting confirmation”.
“Included in the seller's invoice” means count it there once. “Awaiting confirmation” keeps the comparison incomplete; it does not mean €0. For costs that depend on an event, record the trigger and calculation using the additional freight charges checklist.
Confirm the import VAT person and documents
For EU imports, the country of import designates or recognises the person liable for import VAT. Ask your clearance and tax contacts who that is for this purchase, what documents your business will receive, and how payment or accounting will work. Have them confirm any deduction entitlement separately. European Commission: import VAT liability.
Request the import VAT calculation breakdown. The EU framework includes specified duties and incidental expenses in the taxable amount when they are not already included; the goods invoice alone may not be the base. European Commission: import VAT taxable amount.
Keep those answers with the supplier's invoice and the clearance documents. The freight documents guide helps you separate the papers for the goods, transport and insurance.
Send this before accepting the offer
For [goods and quantity], please confirm delivery to [address and exact receiving point] under [DDP or DAP, Incoterms 2020]. State the full invoice amount, currency, tax treatment and payment dates. List what is included and every amount payable separately by us, including import clearance, duties, import VAT and unloading. Identify the clearance contact, the person named for import VAT, and the documents we must supply and will receive. For each open item, name the contact who will confirm it. Please include quotation validity and conditions for price changes.
Send the sale questions to the supplier, import questions to the named clearance contact, and VAT questions to your tax contact. Collect their replies in the same payment record. Then compare complete offers for the same scope and decide which arrangement your business can carry out.
If you also need to choose a separate carrier, use the transport quote comparison for those freight offers. Keep its transport total separate from the goods-sale total so you can see any carriage already included in the supplier's invoice.
Sources and checks
Each date records a check of the stated claim and scope.
- DDP/DAP normal delivery; import allocation; conditional unloading costs; assistance.
Selected Incoterms2020 provisions; B3/B9 exceptions and actual agreement matter. No individual contract or importer eligibility determined. · Checked October 24, 2026
- Sale-contract scope and named point/edition; tariff imposition outside rules.
Selected incorporation/scope paragraphs. No universal adjustment clause, economic-incidence or governing-law outcome certified. · Checked October 12, 2026
- EU import VAT base and first-destination reference.
Commission explanation of Articles85–87. No rate, valuation, actual transaction or national treatment calculated. · Checked October 12, 2026
- Country-designated import VAT payer; conditional deduction.
Commission Article201 explanation. No Portugal/Spain registration, documentation or VAT recovery eligibility confirmed. · Checked October 24, 2026
Ready for the next step?
Turn your shipment details into a clear request.
Prepare your cargo, access and timing details, then compare the scope of each carrier's offer.
Something has changed? Tell us what needs correcting.